House View

House View Q3 2026: Shock absorption​

Our view of global markets

Selectivity matters

  • The global economy is bending under successive shocks, but not breaking. Following the disruption from US tariffs, the Middle East crisis now appears to be stabilising. But oil prices remain elevated, inflation is still above target in most major economies, and the macro backdrop remains vulnerable to renewed volatility ahead of the US mid-term elections.
  • What matters for investors is not just market direction, but the range of possible outcomes. Gaps across regions, asset classes and narratives are widening: the US remains relatively resilient, while Europe and parts of Asia are more sensitive to shifts in energy supply and prices. Markets are sending conflicting signals, with bonds pointing to a more stagflationary path while equities reflect a more optimistic growth backdrop.
  • This divergence is playing out within asset classes. Elevated inflation risk and higher-for-longer rates are shifting attention towards value, income and quality, while AI-led investment supports growth and valuations in parts of the market. Correlations between equities and bonds have risen, making diversification less straightforward and reinforcing the case for a broader toolkit.
  • In this environment, beta alone is unlikely to be sufficient. Returns will depend on careful choices – across countries, sectors and instruments – and the ability to adapt.
  • The durability of any relief rally depends on sustained normalisation of energy flows through the Strait of Hormuz and a credible political settlement. Our base case remains one of resilience – but markets are pricing a reduction in risk, not its removal.
Icon

Chart of the quarter

US tech investment reaches new highs
US IT investment has exceeded its dot‑com era peak as a share of GDP, underlining how the AI cycle is strengthening rather than fading. As this investment broadens beyond a narrow group of firms, identifying the winners becomes more critical for investors – and more challenging.
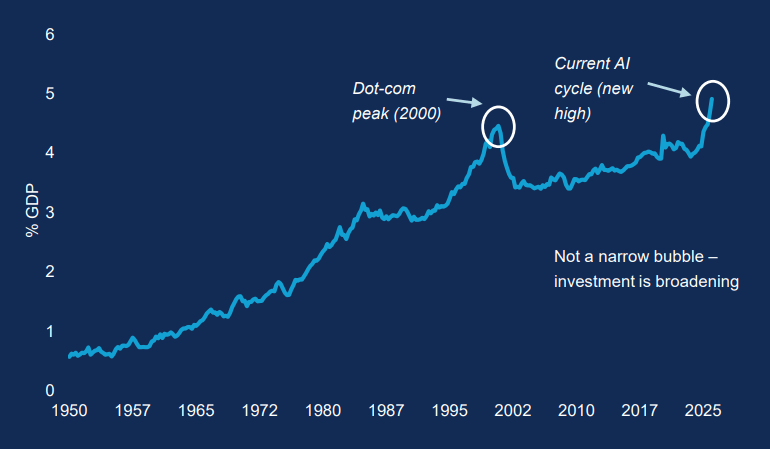
Line chart titled “US tech investment reaches new highs”. The chart shows US IT investment as a percentage of GDP rising from below 1% in 1950 to around 5% in 2025. A previous peak occurs around 2000 (dot-com), followed by a decline and steady increase. The latest data point exceeds the dot-com peak, labeled as a new high. Annotation notes investment is broadening beyond a narrow group of firms.

Source: Bloomberg and AllianzGI Economics & Strategy (data as at May 2026).

Short on time? Download the summary of our House View Q3.
Asset class convictions

Asset class convictions: equities

  • AI infrastructure is shifting from training (building models) to deployment at scale. This is broadening demand beyond graphics processing units (GPUs), pointing to diversified opportunities across semiconductors, data centre equipment, and enabling technologies.
  • Value stocks show promise, providing diversification in an AI-driven market and potentially benefiting from a different macro landscape. After a long period of “Growth” and mega-cap dominance, greater volatility and the spectre of higher-for-longer rates are driving a rotation towards fundamentals.
  • Strategic autonomy continues to grow in importance, and not just in Europe. This is evident from growing government spending on defence, energy and key infrastructure, supporting corporate activity across sectors. Beyond defence, the drive for autonomy is also evident in energy transition, digital and financial infrastructure, and manufacturing.
  • In Asia, equities are well positioned to benefit from global themes, particularly infrastructure, defence, and AI spending. China stands out given the rapid diffusion of AI across its economy. A broad ecosystem is emerging, spanning hardware, software and infrastructure, supported by strong domestic supply chains and deep STEM talent.

The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management's current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.

Asset class convictions: fixed income

  • In the current environment, where the distribution of possible scenarios is unusually wide, security selection increasingly outweighs beta as a driver of return.
  • Yields have risen significantly in core rates markets, yet credit markets have not adjusted, revealing shocks are being absorbed differently across asset classes. Looking across regions and asset types, actively managing duration and focusing on higher‑quality credit can help smooth out volatility in stocks and interest rates.
  • Emerging markets (EM) offer opportunities but demand a selective approach, such as favouring oil exporters over importers. We also like long 15-year Peruvian and 10-year Brazilian local rates.
  • Early signs of a reflationary trend in China could make the renminbi one of the best diversifiers. Consider a structural long renminbi over the US dollar.
  • In credit, we prefer financials and consumer non cyclicals with a tilt towards investment grade, and we are cautious on consumer cyclicals.
  • Despite noise around private credit, overall credit fundamentals remain solid across public credit markets with low default rates. Any spread widening could be a buying opportunity.

The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management's current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.

Asset class convictions: multi asset

  • Despite a fragile geopolitical backdrop, we remain positive on equities, more so from a systematic than fundamental perspective, with a preference for the US and EM over Europe and Japan.
  • With AI also becoming an important driver of EM performance, concentration risk should be managed within a broadly diversified portfolio.
  • In fixed income, we see fundamental value in bonds, even though the market cycle remains challenging. We prefer EM bonds and, within credit, favour US and European investment grade bonds over high yielders.
  • In FX, we have returned to a neutral view on the US dollar after its recent decline. Over the medium term, we see scope for renewed weakness as safe-haven demand eases and valuation and rate headwinds reassert themselves.
  • We are constructive on gold in an environment where questions about central bank independence and the US dollar may return to the fore. We continue to be long commodities as a key diversifier, with our preference for gold balanced by a more neutral stance on gas, oil, copper and silver. Given the uncertainty, we also use option strategies to enhance diversification in many portfolios.

The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management's current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.

Private markets - mid-year outlook

  • Resilience and return potential: Private markets are well positioned to deliver attractive risk-adjusted returns, supported by higher base rates, tighter bank regulation and wider spreads, which continue to create opportunities relative to public markets.
  • Focus on fundamentals: Recent headlines have heightened scrutiny around valuations, redemptions and late-cycle risks, reinforcing a focus on fundamentals, greater transparency and more conservative structures.
  • Diversification remains essential: Allocating across strategies, vintages, geographies and primary and secondary investments helps manage uncertainty, smooth deployment and avoid concentration risks.
  • Rising importance of selectivity: Greater dispersion across assets and managers increases the need for robust underwriting, strong covenants and platforms with deep origination and workout expertise.
  • Secondaries as a core allocation: In our view, LP- and GP-led secondaries provide access to seasoned portfolios, enhanced liquidity and potentially attractive entry points.
  • Infrastructure driven by secular themes: Geopolitical volatility strengthens the case for energy security and independence, while digitalisation and decarbonisation drive demand, particularly in areas such as data centres, grids and storage.
  • Private credit remains compelling: Its growing role in mid-market financing, alongside rising demand for infrastructure credit, direct lending across Europe and Asia, and low-correlation impact strategies, underpins continued growth.
  • Private equity gradually recovering: Improving exit activity may support a recovery, while liquidity constraints continue to drive demand for secondaries.

Our latest thinking on macroeconomics and markets, plus high-conviction ideas from our asset class CIOs.

Our full House View includes comprehensive analysis and proprietary data on investment markets.
Download PDF
This is a summary of our House View Q3 2026
Download PDF

This document reflects the views of Allianz Global Investors’ investment leadership going into Q3 2026. Past performance does not predict future returns. The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management’s current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.

Investing involves risk. The value of an investment and the income from it may fall as well as rise and investors might not get back the full amount invested.

Past performance does not predict future returns. If the currency in which the past performance is displayed differs from the currency of the country in which the investor resides, then the investor should be aware that due to the exchange rate fluctuations the performance shown may be higher or lower if converted into the investor’s local currency.

This is for information only and not to be construed as a solicitation or an invitation to make an offer to buy or sell any securities. The views and opinions expressed herein, which are subject to change without notice, are those of the issuer or its affiliated companies at the time of publication. The data used is derived from various sources and assumed to be accurate and reliable at the time of publication, but it has not been independently verified; its accuracy or completeness is not guaranteed and no liability is assumed for any direct or consequential losses arising from its use, unless caused by gross negligence or willful misconduct. The duplication, publication, extraction or transmission of the contents, irrespective of the form, is not permitted, except for the case of explicit permission by Allianz Global Investors.

This material has not been reviewed by any regulatory authorities.

This document is being distributed by the following Allianz Global Investors companies: In Australia, this material is presented by Allianz Global Investors Asia Pacific Limited (“AllianzGI AP”) and is intended for the use of investment consultants and other institutional/professional investors only, and is not directed to the public or individual retail investors. AllianzGI AP is not licensed to provide financial services to retail clients in Australia. AllianzGI AP is exempt from the requirement to hold an Australian Foreign Financial Service License under the Corporations Act 2001 (Cth) pursuant to ASIC Class Order (CO 03/1103) with respect to the provision of financial services to wholesale clients only. AllianzGI AP is licensed and regulated by Hong Kong Securities and Futures Commission under Hong Kong laws, which differ from Australian laws; in the European Union, by Allianz Global Investors GmbH, an investment company in Germany, authorized by the German Bundesanstalt für Finanzdienstleistungs-aufsicht (BaFin) and is authorized and regulated in South Africa by the Financial Sector Conduct Authority; in the UK, by Allianz Global Investors (UK) Ltd. company number 11516839, authorised and regulated by the Financial Conduct Authority (FCA); in Switzerland, by Allianz Global Investors (Schweiz) AG, authorised by the Swiss financial markets regulator (FINMA); in HK, by Allianz Global Investors Asia Pacific Ltd., licensed by the Hong Kong Securities and Futures Commission; in Singapore, by Allianz Global Investors Singapore Ltd., regulated by the Monetary Authority of Singapore [Company Registration No. 199907169Z]; in Japan, by Allianz Global Investors Japan Co., Ltd., registered in Japan as a Financial Instruments Business Operator [Registered No. The Director of Kanto Local Finance Bureau (Financial Instruments Business Operator), No. 424], Member of Japan Investment Advisers Association, the Investment Trust Association, Japan and Type II Financial Instruments Firms Association; In mainland China, it is for Qualified Domestic Institutional Investors scheme pursuant to applicable rules and regulations and is for information purpose only; in Taiwan, by Allianz Global Investors Taiwan Ltd., licensed by Financial Supervisory Commission in Taiwan; in Indonesia, by PT. Allianz Global Investors Asset Management Indonesia licensed by Indonesia Financial Services Authority (OJK); and in the Abu Dhabi Global Market by Allianz Global Investors Middle East Limited, which is authorised and regulated by the ADGM Financial Services Regulatory Authority.

Admaster: 5554717

House View archives

Global markets enter the second quarter navigating a more complex backdrop than many expected at the start of the year. Growth slows yet stays resilient; sticky inflation could delay rate cuts and keep policy tight. We prioritise selective duration, quality carry, AI linked equities and remain cautious on the US dollar.

Discover more

The global economy enters 2026 bending but not breaking. We expect growth to stay on track, creating an environment that favours risk-taking. Expect a resilient yet complex year where active management will be critical.

Discover more

Markets are coming to terms with a new reality that requires caution. But this evolving backdrop may open the door to opportunities for actively positioned investors.

Discover more

Allianz Global Investors

You are leaving this website and being re-directed to the below website outside Hong Kong. This does not imply any approval or endorsement of the information by Allianz Global Investors contained in the redirected website nor does Allianz Global Investors accept any responsibility or liability in connection with this hyperlink and the information contained herein. Please keep in mind that the redirected website may contain funds and strategies not authorized for offering to the public of Hong Kong. Besides, please also take note of the redirected website's terms and conditions, privacy and security policies, and other legal information. By clicking "Continue", you confirm that you acknowledge the details mentioned above and would like to continue accessing the redirected website. Please click "Stay here" if you have any concerns.

Welcome to Allianz Global Investors

Select your language
  • 中文(繁體)
  • English
Select Role
  • Retail Investor
  • Institutional Investors
  • Pension Investors
  • Allianz Global Investors Fund (“AGIF”)

     • Allianz Global Investors Fund (“AGIF”) as an umbrella fund under the UCITS regulations has within it different Sub-Funds investing in fixed income securities, equities, and derivative instruments, each with a different investment objective and/or risk profile.

    • All Sub-Funds may invest in financial derivative instruments (“FDI”) which may expose to higher leverage, counterparty, liquidity, valuation, volatility, market and over the counter transaction risks. A Sub-Fund’s net derivative exposure may be up to 50% of its net asset value (“NAV”). 

    • Some Sub-Funds as part of their investments may invest in any one or a combination of the instruments such as fixed income securities, emerging market securities, and/or mortgage-backed securities, asset-backed securities, property-backed securities (especially REITs) and/or structured products and/or FDI, exposing to various potential risks (including leverage, counterparty, liquidity, valuation, volatility, market, fluctuations in the value of and the rental income received in respect of the underlying property, and over the counter transaction risks). 

    • Some Sub-Funds may invest in single countries or industry sectors (in particular small/mid cap companies) which may reduce risk diversification. Some Sub-Funds are exposed to significant risks which include investment/general market, country and region, emerging market (such as Mainland China), creditworthiness/credit rating/downgrading, default, asset allocation, interest rate, volatility and liquidity, counterparty, sovereign debt, valuation, credit rating agency, company-specific, currency (in particular RMB), RMB debt securities and Mainland China tax risks. 

    • Some Sub-Funds may invest in convertible bonds, high-yield, non-investment grade investments and unrated securities that may be subject to higher risks (including volatility, loss of principal and interest, creditworthiness and downgrading, default, interest rate, general market and liquidity risks) and therefore may adversely impact the net asset value of the Sub-Funds. Convertibles will be exposed prepayment risk, equity movement and greater volatility than straight bond investments.

    • Some Sub-Funds may invest a significant portion of the assets in interest-bearing securities issued or guaranteed by a non-investment grade sovereign issuer (e.g. Philippines) and is subject to higher risks of liquidity, credit, concentration and default of the sovereign issuer as well as greater volatility and higher risk profile that may result in significant losses to the investors. 

    • Some Sub-Funds may invest in European countries. The economic and financial difficulties in Europe may get worse and adversely affect the Sub-Funds (such as increased volatility, liquidity and currency risks associated with investments in Europe).

    • Some Sub-Funds may invest in the China A-Shares market, China B-Shares market and/or debt securities directly via the Stock Connect or the China Interbank Bond Market or Bond Connect or other foreign access regimes and/or other permitted means and/or indirectly through all eligible instruments and thus is subject to the associated risks (including quota limitations, change in rule and regulations, repatriation of the Sub-Fund’s monies, trade restrictions, clearing and settlement, China market volatility and uncertainty, China market volatility and uncertainty, potential clearing and/or settlement difficulties, change in economic, social and political policy in the PRC and Mainland China tax risks).  

    • Some Sub-Funds may adopt the following strategies, Socially Responsible Investment (Proprietary Scoring) Strategy, SDG-Aligned Strategy, Sustainability Key Performance Indicator Strategy (Relative), Green Bond Strategy, Multi Asset Sustainable Strategy, Sustainability Key Performance Indicator Strategy (Absolute Threshold), Environment, Social and Governance (“ESG”) Score Strategy, and Sustainability Key Performance Indicator Strategy (Absolute). The Sub-Funds may be exposed to sustainable investment risks relating to the strategies (such as foregoing opportunities to buy certain securities when it might otherwise be advantageous to do so, selling securities when it might be disadvantageous to do so, and/or relying on information and data from third party ESG research data providers and internal analyses which may be subjective, incomplete, inaccurate or unavailable and/or reducing risk diversifications compared to broadly based funds). Also, some Sub-Funds may be particularly focusing on the greenhouse gas emissions (“GHG”) efficiency of the investee companies rather than their financial performance. These may have an adverse impact on the performance of the Sub-Funds.

    • Some Sub-Funds may invest in share class with fixed distribution percentage (Class AMf). Investors should note that fixed distribution percentage is not guaranteed. The share class is not an alternative to fixed interest paying investment. The percentage of distributions paid by these share classes is unrelated to expected or past income or returns of these share classes or the Sub-Funds. Distribution will continue even the Sub-Fund has negative returns and may adversely impact the net asset value of the Sub-Fund.  Positive distribution yield does not imply positive return.

    • Investment involves risks that could result in loss of part or entire amount of investors’ investment.

    • In making investment decisions, investors should not rely solely on this [website/material].


    Note: Dividend payments may, at the sole discretion of the Investment Manager, be made out of the Sub-Fund’s capital or effectively out of the Sub-Fund’s capital which represents a return or withdrawal of part of the amount investors originally invested and/or capital gains attributable to the original investment. This may result in an immediate decrease in the NAV per share and the capital of the Sub-Fund available for investment in the future and capital growth may be reduced, in particular for hedged share classes for which the distribution amount and NAV of any hedged share classes (HSC) may be adversely affected by differences in the interests rates of the reference currency of the HSC and the base currency of the respective Sub-Fund, particularly if such HSC are applying the IRD Neutral Policy. Dividend payments are applicable for Class A/AM/AMg/AMi/AMgi/AQ Dis (Annually/Monthly/Quarterly distribution) and for reference only but not guaranteed.  Positive distribution yield does not imply positive return. For details, please refer to the Sub-Fund’s distribution policy disclosed in the offering documents.


    Allianz Global Investors Asia Fund

    • Allianz Global Investors Asia Fund (the “Trust”) is an umbrella unit trust constituted under the laws of Hong Kong pursuant to the Trust Deed. Allianz Thematic Income and Allianz Selection Income and Growth and Allianz Yield Plus Fund are the sub-funds of the Trust (each a “Sub-Fund”) investing in fixed income securities, equities and derivative instruments, each with a different investment objective and/or risk profile.

    • Some Sub-Funds are exposed to significant risks which include investment/general market, company-specific, emerging market, creditworthiness/credit rating/downgrading, default, volatility and liquidity, valuation, sovereign debt, thematic concentration, thematic-based investment strategy, counterparty, interest rate changes, country and region, asset allocation risks and currency (such as exchange controls, in particular RMB), and the adverse impact on RMB share classes due to currency depreciation.  

    • A Sub-Fund may invest in asset-backed securities (“ABS”) and mortgage-backed securities (“MBS”) which may be highly illiquid and prone to substantial price volatility. These instruments may be subject to greater general market risk, concentration risk, credit and counterparty default risk, liquidity risk and interest rate risk compared to other debt securities.

    • Some Sub-Funds may invest in high-yield (non-investment grade and unrated) investments and convertible bonds which may be subject to higher risks, such as volatility, creditworthiness, default, interest rate changes, general market and liquidity risks and therefore may  adversely impact the net asset value of the Sub-Fund. 

    • All Sub-Funds may invest in financial derivative instruments (“FDI”) which may expose to higher leverage, counterparty, liquidity, valuation, volatility, market and over the counter transaction risks.  The use of derivatives may result in losses to the Sub-Funds which are greater than the amount originally invested. A Sub-Fund’s net derivative exposure may be up to 50% of its net asset value (“NAV”).

    • These investments may involve risks that could result in loss of part or entire amount of investors’ investment.

    • In making investment decisions, investors should not rely solely on this website.

    Note: Dividend payments may, at the sole discretion of the Investment Manager, be made out of the Sub-Fund’s income and/or capital which in the latter case represents a return or withdrawal of part of the amount investors originally invested and/or capital gains attributable to the original investment. This may result in an immediate decrease in the NAV per distribution unit and the capital of the Sub-Fund available for investment in the future and capital growth may be reduced, in particular for hedged share classes for which the distribution amount and NAV of any hedged share classes (HSC) may be adversely affected by differences in the interests rates of the reference currency of the HSC and the base currency of the Sub-Fund, particularly if such HSC are applying the IRD Neutral Policy. Dividend payments are applicable for Class A/AM/AMg/AMi/AMgi Dis (Annually/Monthly distribution) and for reference only but not guaranteed.  Positive distribution yield does not imply positive return. For details, please refer to the Sub-Fund’s distribution policy disclosed in the offering documents.

Please indicate you have read and understood the Important Notice.